If you want to maximize your payout when selling shares, bonds or any other asset, you need to understand capital gains tax. Failing to do so can be a hefty surprise and greatly affect the return on your investment.
If you, like me, are someone who builds wealth by building, buying and selling assets like businesses and equities, you may also be interested in finding ways to reduce or even eliminate your capital gains tax liability.
Fortunately, for expats and online entrepreneurs, you have options. One of these involves low or no capital gains tax countries.
In this article, I’ll walk you through some of the best countries for reducing your capital gains tax liability, along with some of the benefits and considerations of living in each country.
What Is CGT? Why Does It Matter?
Capital gains tax or CGT is a type of income tax that applies to the difference between an asset’s selling price and purchase price.
For example, if you buy a share for $100 and sell it for $150, you have a capital gain of $50, which may be subject to tax depending on:
- the country you reside in,
- the type of asset,
- the holding period, and
- your personal income level.
Capital gains tax matters because it can significantly affect your net return on investment. For instance, if you live in a country that has a high capital gains tax rate, you may end up paying a large portion of your profits to the government.
On the other hand, if you live in a country that has a low or zero capital gains tax rate, you can keep more of your profits and reinvest this to create multiple sources of income.
Which Countries Have No Capital Gains Tax?
Several income tax free countries do not impose capital gains tax on certain types of assets or under certain conditions.
The useful comparison is between exemptions for particular private investments and the wider taxes you would pay after a move. The examples below include genuine exemptions and countries commonly mislabelled as tax-free.
- Andorra
- The Bahamas
- Belgium
- Hong Kong
- Luxembourg
- Malaysia
- Monaco
- Netherlands
- New Zealand
- Switzerland
- Singapore
- Thailand
- United Arab Emirates
However, understanding which countries have no capital gains tax is only the start of the discussion. In order to benefit from this situation, you’ll need to become a tax resident there.
So with that in mind, it’s also important to understand the ease of qualifying for zero capital gains tax, the cost of living situation, as well as what is required to become a resident in that country in the first place.
Below are the places I would investigate, with the important limitations alongside the attractions. Belgium, the Netherlands and Thailand are included to explain why the simple “no CGT” label can mislead.
Andorra
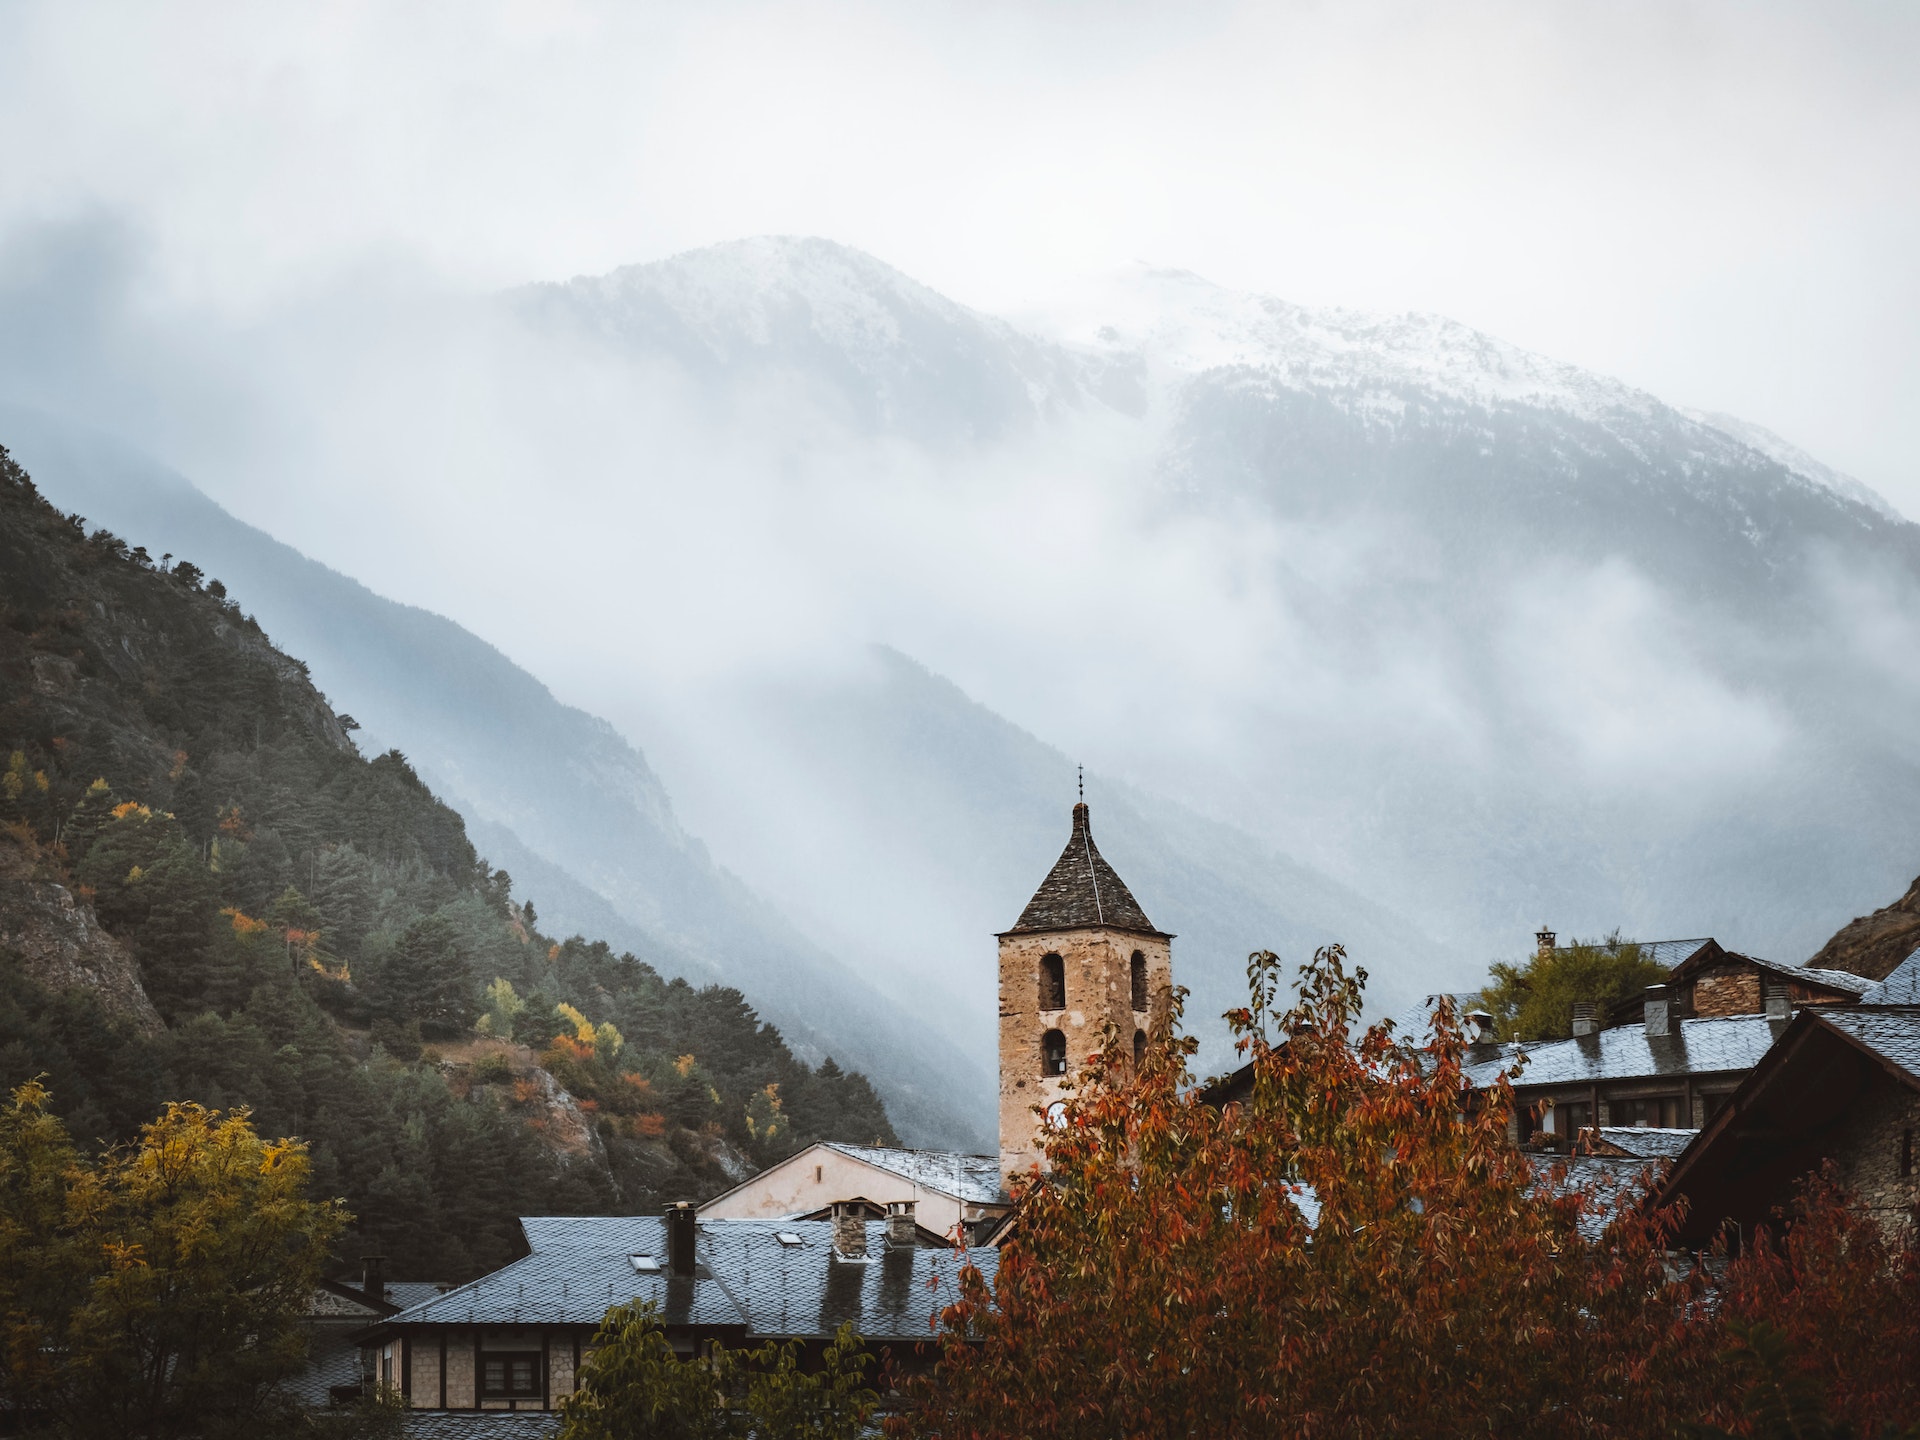
Andorra can be attractive for a private investor, but “0–15%” is no longer a reliable property-gains summary. Qualifying share gains can be exempt where the relevant combined holding has not exceeded 25% during the preceding twelve months, or where the larger holding meets the ten-year condition. Check related-party aggregation and the exact asset.
Property gains sit within the income-tax system, with additional short-holding charges and long-holding reliefs. I cover the conditions in the Andorra tax guide. For a move, compare the current residence routes as well: the cheapest permit minimum is not a tax-residence test.
The Bahamas
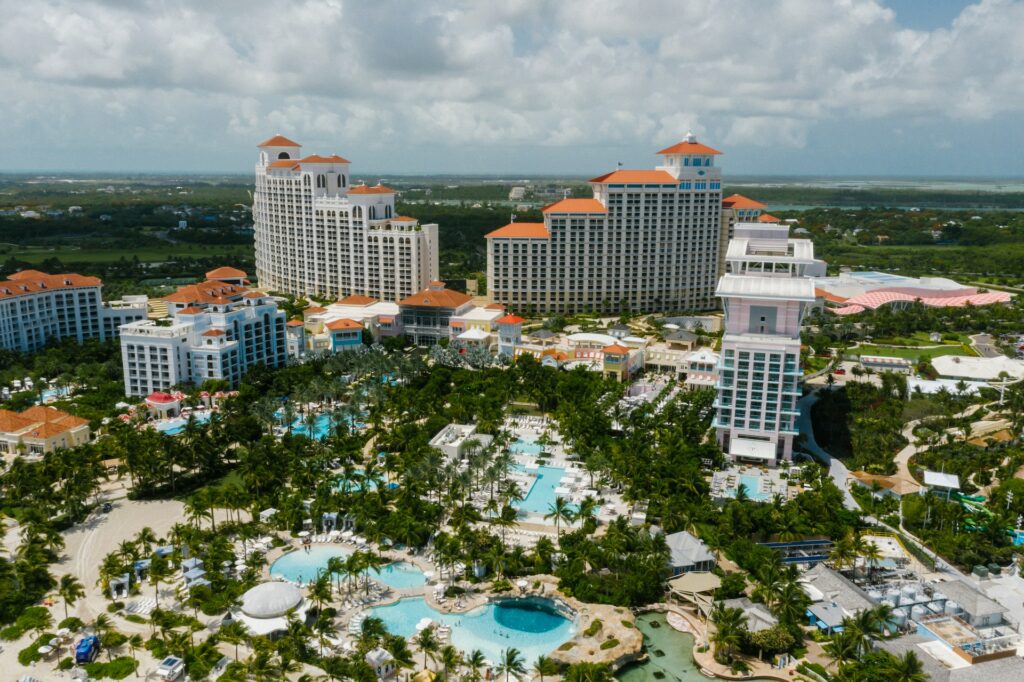
The Bahamas generally has no personal income or capital gains tax. It does have other taxes and fees, and becoming a resident there does not cancel US citizenship-based taxation or continuing liabilities elsewhere.
The economic permanent residence investment threshold rose to BSD 1 million in 2025, with qualifying investments and a ten-year holding condition. That is different from an annual permit and should not be confused with the old $250,000 or $750,000 figures. UNCTAD’s summary, linked to the amending law.
For me, the decision would still come down to the islands, travel connections and a realistic housing budget. A tax saving is not much help if you dislike the place you have to live.
Belgium
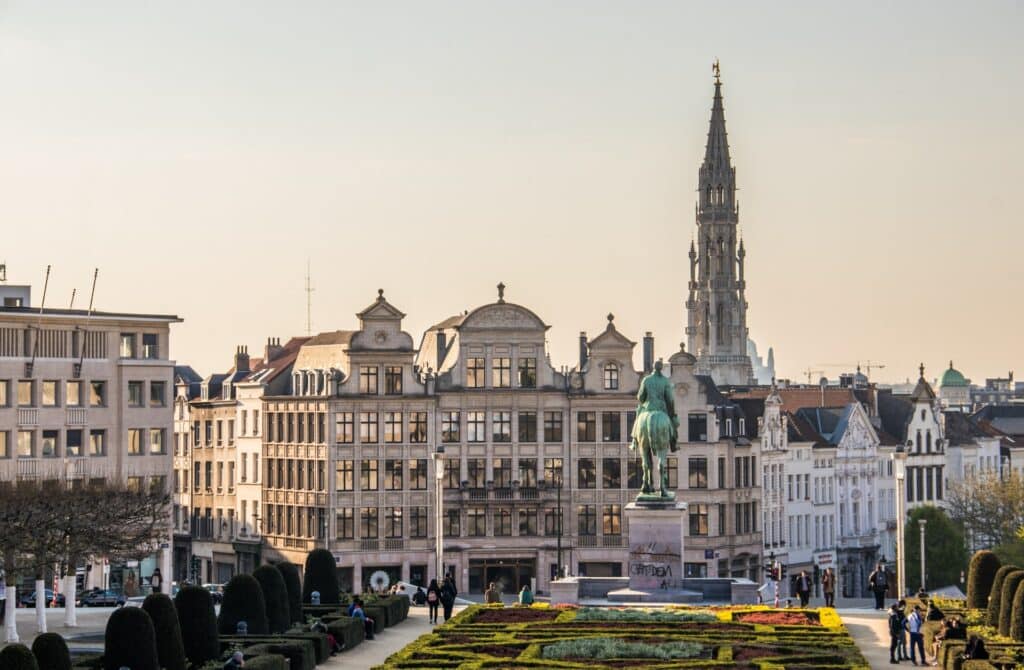
Belgium belongs here as a warning against relying on an old “tax-free shares” list. Its 2026 financial capital-gains regime generally introduces a 10% charge on relevant gains from 1 January 2026, with an allowance, valuation rules and different treatment for certain holdings and transactions.
Holding shares for six months does not create the blanket exemption described in older versions of this guide. Professional or speculative income and substantial holdings require separate analysis. Cross-check the legislative file and Belfius’s implementation guidance.
Belgium may suit your work or family beautifully. It should no longer make your shortlist on the assumption that ordinary financial gains are all exempt.
Hong Kong
Hong Kong generally distinguishes capital disposals from taxable trading profits. That is an assessment of the facts, not a rule that any sale called an investment is exempt. Employee share benefits have their own income-tax treatment.
For companies in multinational groups, the foreign-sourced income exemption rules can also bring specified foreign disposal gains into scope unless conditions are met. That corporate regime is different from an individual selling a personal investment.
Match the structure, source of profit and actual activities to the rules. Incorporating a company, obtaining an immigration permit and becoming tax resident are separate decisions.
Luxembourg
For private shares held for more than six months, the size and history of the holding matter. A non-substantial holding may qualify for exemption; a substantial holding, broadly more than 10% including the specified family interests during the preceding five years, has different treatment. Short-term disposals are also different.
The official share-disposal guide explains these distinctions. It does not support a blanket “all assets tax-free after six months” claim. Property, business assets and employment-related benefits need their own analysis.
Luxembourg’s business connections may be useful, but expensive housing and ordinary income taxes belong in the same budget as any investment exemption.
Malaysia
A private investor’s capital disposal and the profits of a trading business are different things in Malaysia. Property and shares in real-property companies can fall under real property gains tax; capital-gains rules also apply to specified entities and transactions. A list of stock exchanges does not make business trading profits automatically exempt.
Foreign-source income remitted to Malaysia has separate rules and conditional exemptions for individuals. Check the Revenue Board’s explanation of taxable income alongside a current income-category summary.
If you are considering a move, MM2H is open under revised categories rather than simply “on hold”. Its deposit, property and stay conditions are separate from the tax treatment of your portfolio.
Monaco
Monaco generally does not tax a resident individual’s private capital gains through a personal income tax. French nationals can fall under the Franco-Monegasque arrangements, and income or gains may remain taxable in another country because of the asset, residence rules or citizenship.
Suitable accommodation and sufficient resources are part of the government’s residence requirements. A bank’s commercial account minimum is not the same as a government investment contribution.
Treat the right to live there, evidence of actual residence and the tax position in the country you leave as three checks. The cost and limited choice of housing can be decisive.
Netherlands
The Netherlands is not a tax-free investment destination. Private savings and investments can be taxed through Box 3, while substantial company interests and business activity belong in different boxes.
For 2026, Box 3 uses a 36% tax rate on the calculated taxable return, not 36% of the whole portfolio. The provisional calculation uses asset-specific assumed returns, and the tax authority explains the lower actual-return adjustment. The old fixed return percentages and claim that actual performance never matters are stale.
The housing market, employment opportunities and family ties might make this the right country for you. Calling the system “no capital gains tax” without describing Box 3 would hide the most relevant part of the comparison.
New Zealand
New Zealand has no comprehensive stand-alone capital gains tax, but many receipts are taxable under ordinary income rules. A share sale can be taxable because of your acquisition purpose, a dealing business or a profit-making scheme; one transaction can be enough.
The Inland Revenue share-investment guide also explains the foreign investment fund rules. These can apply to foreign portfolios even without selling, so “hold foreign shares and pay nothing” is not a sound summary.
Property, intellectual property and selling a business need separate analysis. Immigration permission and the tax consequences of moving are also distinct from whether a particular disposal counts as income.
Switzerland
Gains on privately held movable assets, including ordinary investment securities, are generally exempt at federal and cantonal levels. Professional securities dealing is treated differently; dividends and interest are not the same as an exempt capital gain.
All cantons tax property gains, and cantonal wealth taxes can matter even when private securities gains are exempt. The Federal Tax Administration’s tax-system guide explains the distinction; article 16 of the federal income-tax law provides the private-capital principle.
Check your trading pattern, assets and intended canton before assuming the exemption applies. Mountains and excellent services are a real attraction, but the total cost of living and income tax need an equally serious look.
Singapore
Singapore generally does not tax gains from disposing of personal investments. Gains that amount to a trading or business activity can be taxable. That distinction is more useful than saying it “abolished tax on every asset”. IRAS explains the personal-investment principle.
Property transactions can involve stamp duties and other rules regardless of whether there is a taxable capital gain. Company receipts and foreign disposal gains can also have a different treatment from a private portfolio.
Immigration is selective. An Employment Pass, EntrePass or Global Investor Programme application each has its own conditions; investing through a Singapore account does not itself give permission to live there.
Thailand
Thailand taxes many gains as ordinary income, with specific exemptions such as qualifying listed-share transactions. It should not be presented as a general zero-capital-gains country.
The old advice to wait until the next calendar year before bringing foreign income into Thailand is no longer reliable. For relevant foreign income arising from 2024 while Thai tax resident, remitting in a later year can still trigger tax. The Revenue Department’s foreign-income guide explains the residence, remittance and foreign-tax-credit framework.
Visa permission is separate. The Destination Thailand Visa can suit qualifying remote workers, but it is not a blanket tax exemption or permission for every kind of local work.
United Arab Emirates
The UAE does not have a general personal income tax on wages. Under the corporate-tax framework for natural persons, qualifying personal investment and real-estate investment income are excluded from business activity. An individual conducting a business can nevertheless enter the corporate-tax regime where the conditions, including the AED 1 million turnover threshold, are met.
The Federal Tax Authority’s natural-person guidance sets out that distinction. Owning assets personally and trading through a company should not be treated as interchangeable.
Residence visas have different categories and thresholds. Check the intended route, actual tax-residence position and any continuing tax in the country you leave before budgeting on tax-free gains.
Considerations Before Moving to a Country Without Capital Gains Tax
Before you pack your bags and book your flight, there are some key considerations—not all zero-tax countries are created equal, and not all assets are treated the same way.
Consider factors such as the residency requirements, your asset’s physical location, the ownership structure and other taxes you might qualify for upon the sale of your assets.
Moving to a zero-tax country can be a smart way to save on capital gains tax and grow your wealth faster. However, it is not a decision that should be taken lightly or without proper research and planning.
Before moving, have the specific asset, ownership structure, departure rules and destination tax treatment checked together. A headline exemption is a starting point, not the whole plan.